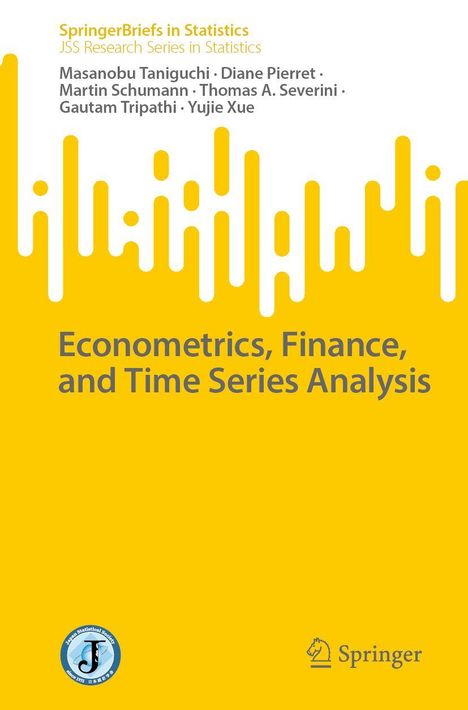
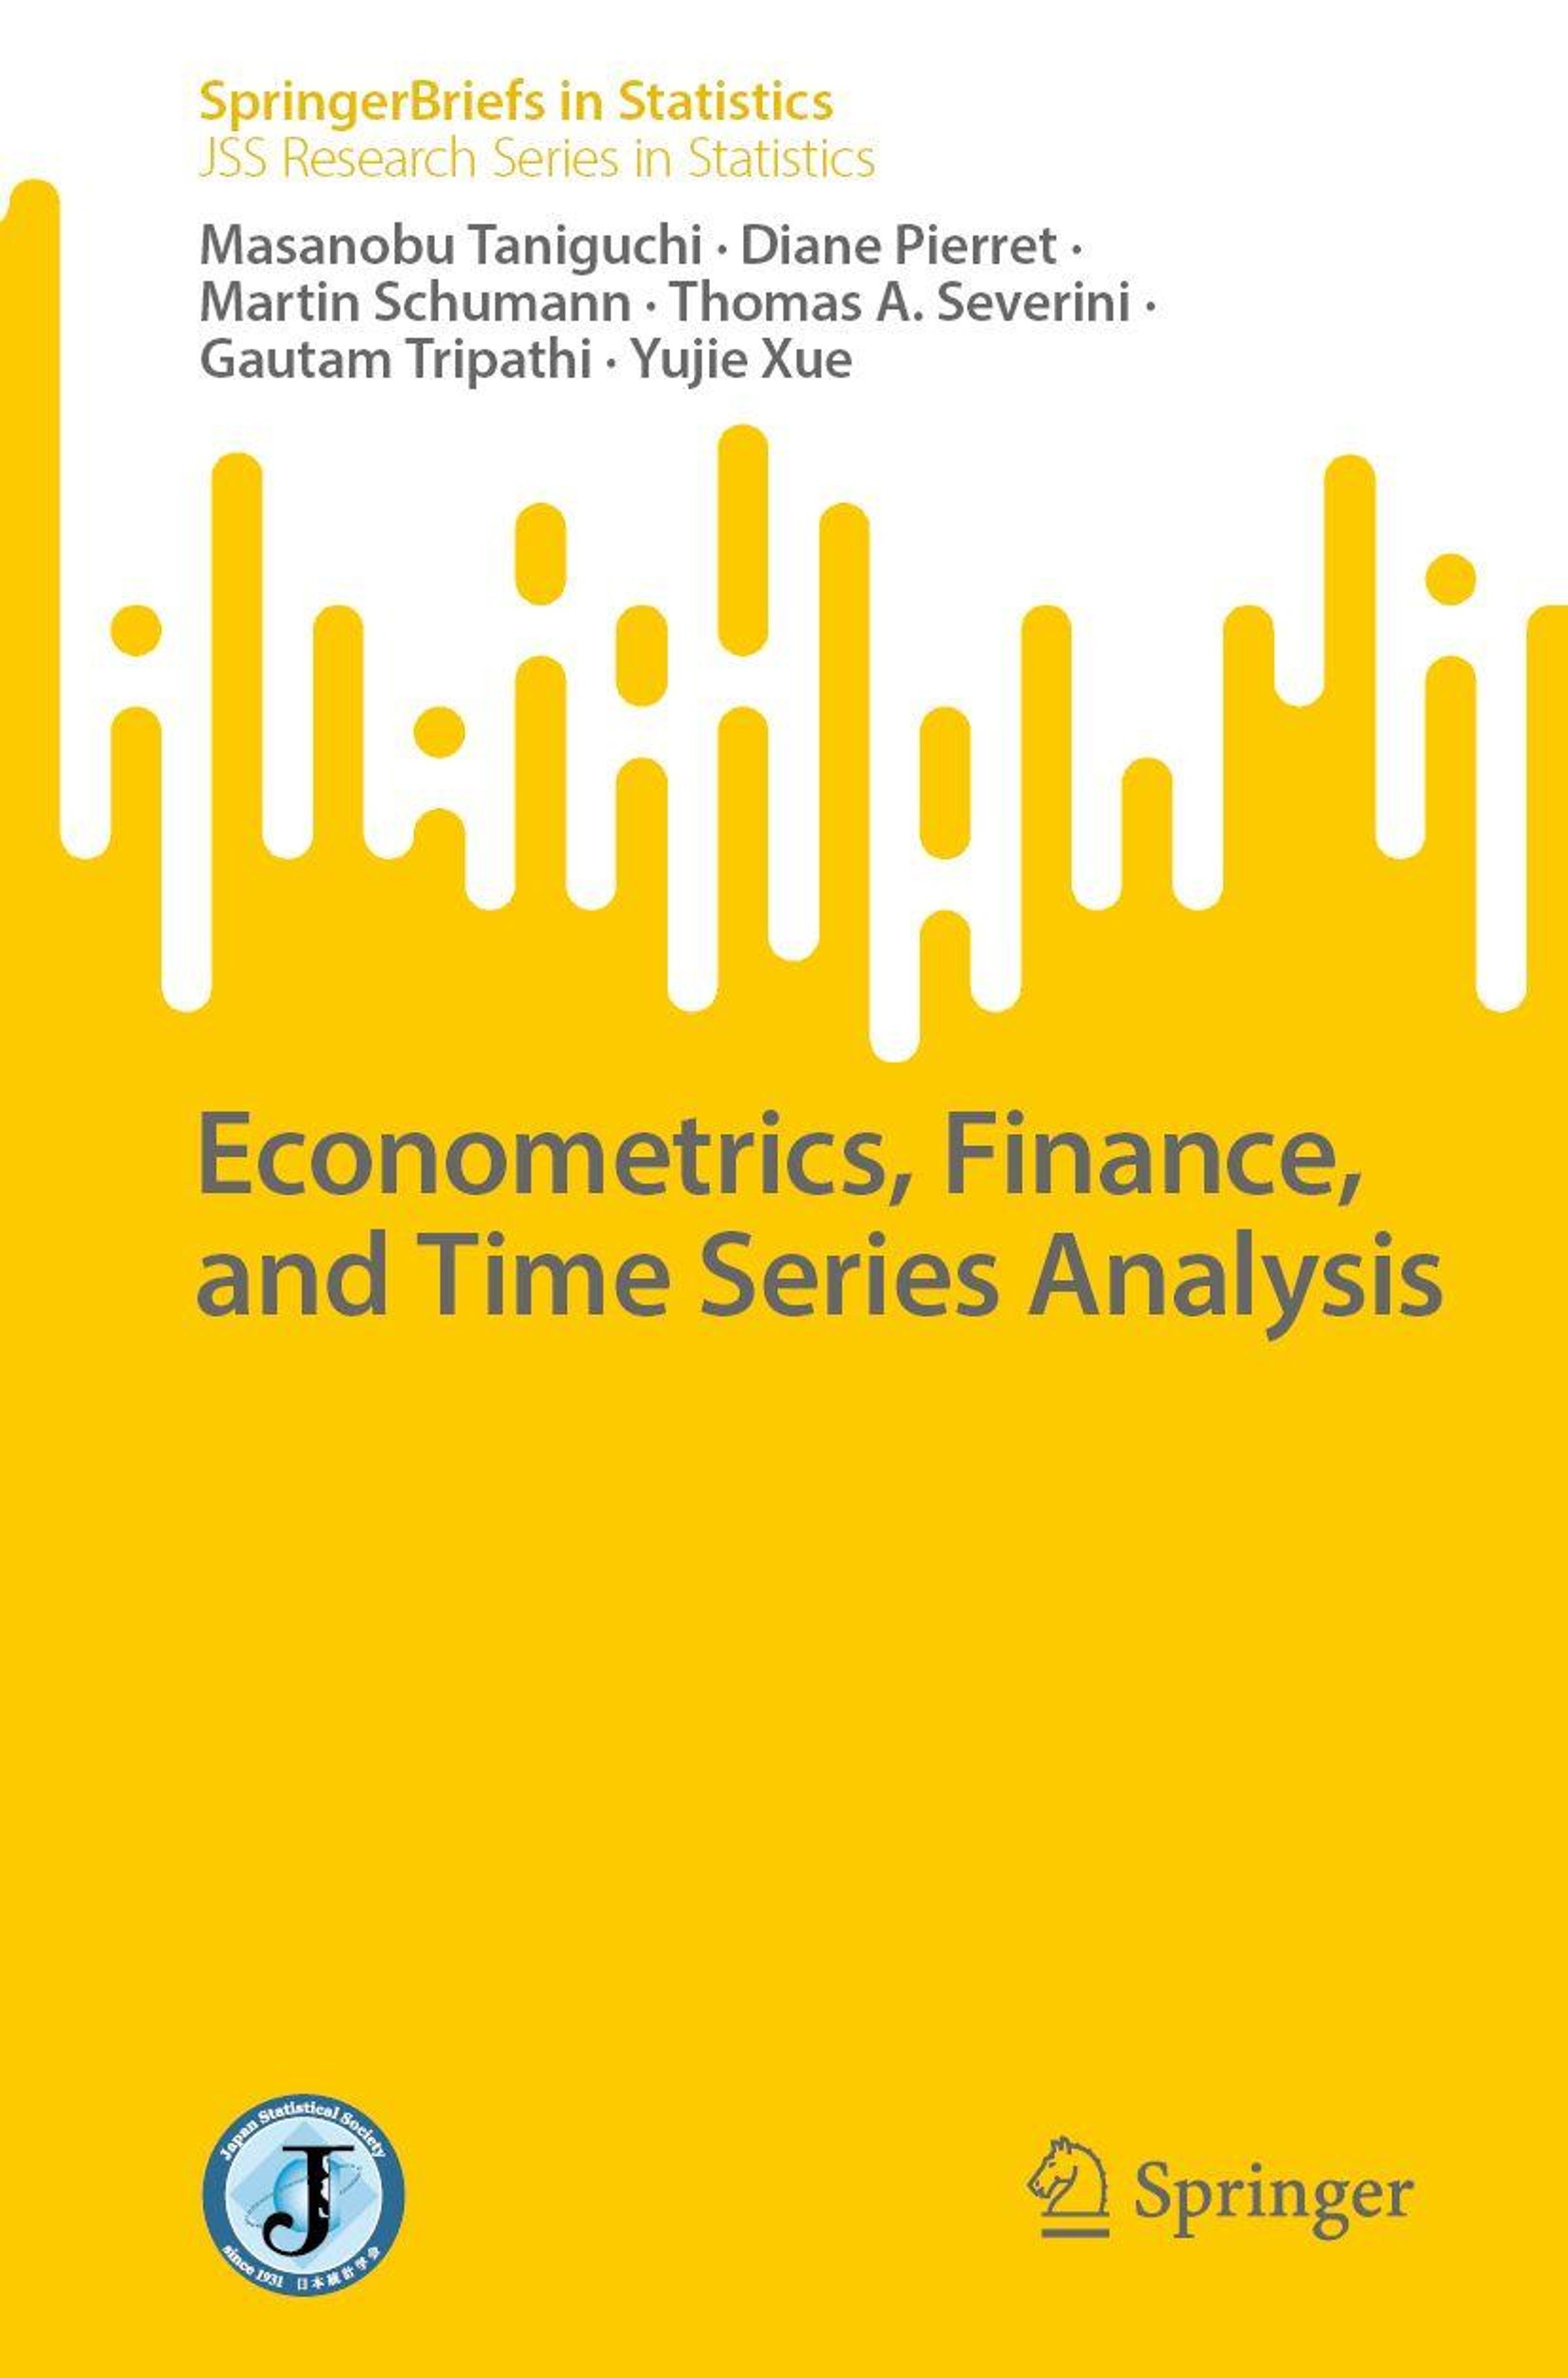
Masanobu Taniguchi: Econometrics, Finance, and Time Series Analysis, Kartoniert / Broschiert
Econometrics, Finance, and Time Series Analysis
(soweit verfügbar beim Lieferanten)
- Verlag:
- Springer, 07/2026
- Einband:
- Kartoniert / Broschiert
- Sprache:
- Englisch
- ISBN-13:
- 9789819580446
- Artikelnummer:
- 12858383
- Umfang:
- 136 Seiten
- Gewicht:
- 219 g
- Maße:
- 235 x 155 mm
- Stärke:
- 8 mm
- Erscheinungstermin:
- 16.7.2026
- Serie:
- SpringerBriefs in Statistics
- Hinweis
-
Achtung: Artikel ist nicht in deutscher Sprache!
Klappentext
This book provides a new contemporary time series approach for econometrics and finance. In a concrete manner a very general divergence between spectra is introduced, resulting in the development of a statistical inference that is efficient and robust, and leads to a new perspective. A measure of systemic risk is also developed in the energy market, which quantifies the cost of energy asset distress vis-à-vis the broader economy during crises, and examines the dynamic interaction between solvency and funding liquidity risk in banks using a panel vector autoregressive (VAR) model. This step shows that a forward-looking measure of capital shortfall under stress is both a predictor and an outcome of funding liquidity risk. Additionally, a new integrated likelihood-based approach for estimating nonlinear panel data models is described. Unlike existing integrated likelihoods, the new integrated likelihood is closer to a genuine likelihood. The book explains why this is due to first-order information unbiasedness, and why it seems to matter more for inference than for estimation. Results of studies in econometrics are provided for support.